The Working Owner Discount: How Owner Dependency Cuts Valuations by Nearly Half (and the Systems That Close It)
If your company cannot run for 30 days without you, the market already knows. Buyers price that reality as a permanent discount.
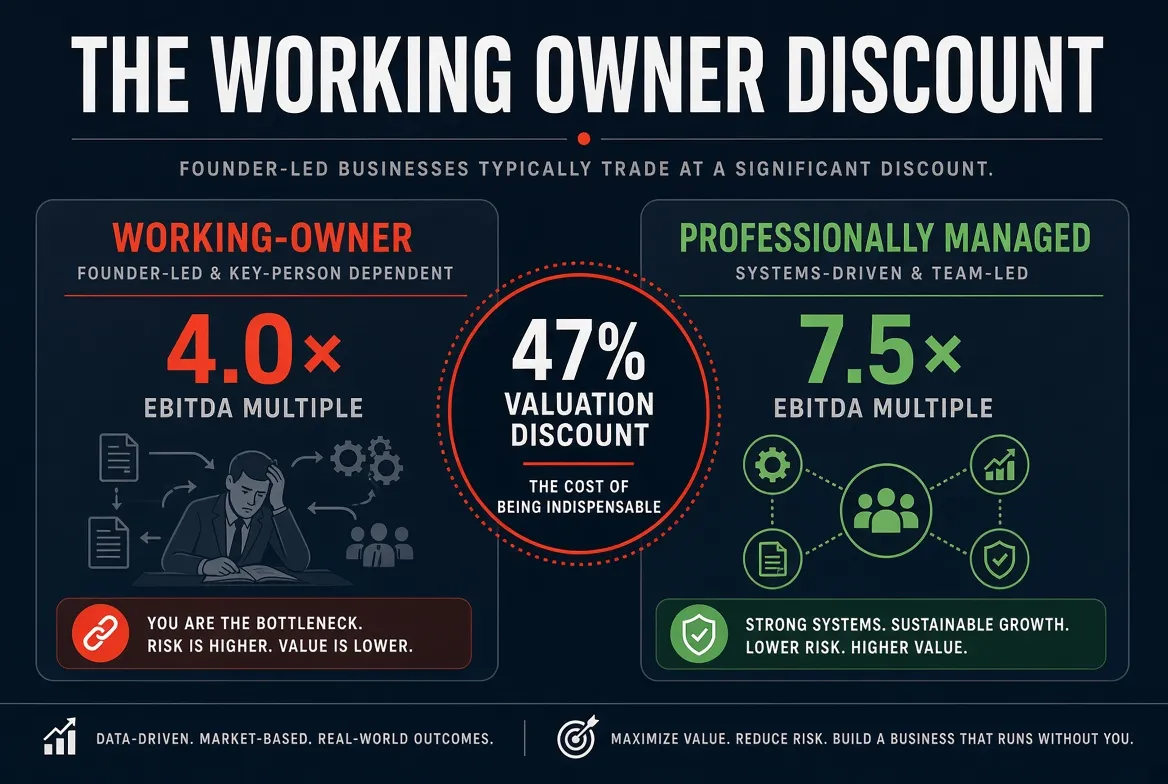
Stratford Analytics examined more than 4,700 U.S. manufacturing transactions (DealStats, 2015–2025). Firms still run by a working owner sold at a median 4.0× MVIC/EBITDA. Professionally managed peers cleared 7.5×. That is a 47% gap—the Working Owner Discount.
Median MVIC/Sales was 0.49× versus 0.86×. Median SDE margins were 12.5% versus 20%. Median time to close stretched to 11.3 months versus 7.5 months. The pattern held across cycles. Documented SOPs correlated with roughly 0.25× higher sales multiples. Businesses that had already transitioned real leadership authority closed 27% faster.
A side-by-side case of two similar machine shops (~$8.9 million revenue, ~$1 million normalized EBITDA) illustrates the arithmetic. The owner-dependent shop cleared 5.4×. The professionalized shop cleared 8.5×. Roughly $3 million stayed on the table solely because one still depended on the owner.
While the sample is manufacturing, the mechanism is not. Across lower-middle-market service and founder-led businesses, Stratford estimates the Working-Owner Discount can reduce exit proceeds by 25–40%, and that owners who professionalize can capture valuation premiums of 1–3× EBITDA. The penalty shows up when the founder remains the operating system—through lower multiples, earnouts, longer diligence, or both. For companies in the $1–25 million revenue band with 5–50 employees, this is usually the single largest controllable gap between what an owner believes the business is worth and what a buyer will actually pay.
Why the Discount Exists
Buyers underwrite future cash flow, not past heroics. When continuity risk (tacit knowledge leaves with the owner), customer risk (relationships sit with one person), and scalability risk (growth is capped by the founder’s bandwidth) are all present, the buyer raises the discount rate or simply pays less. The earnings may be identical; the transferability is not.
Three structural risks drive the discount:
Continuity risk. The buyer models the probability that key operational knowledge, decision frameworks, and problem-solving heuristics disappear on day one after close. Without a documented transfer mechanism, that probability is high.
Customer risk. When primary relationships, pricing authority, and exception handling sit with the founder, revenue is partially personal. Post-close attrition risk gets priced in, often through earnouts or lower headline multiples.
Scalability risk. Growth is limited by the owner’s available hours. Buyers discount businesses that cannot expand without adding the founder’s time proportionally.
The discount is steepest under roughly $10 million in revenue, where institutional buyers see the highest key-person concentration. It is addressable precisely because it is structural rather than market-driven.
The Generational Exit Wave Makes Delay Expensive
Exit Planning Institute’s 2025 Generational State of Owner Readiness report (drawing on the 2023 national survey of 1,162 owners) shows 75% of owners plan to exit within ten years—potentially 4.5 million privately held businesses and $14 trillion in wealth.
Readiness is uneven by generation:
Baby Boomers show the lowest formal exit-planning education (~42%) and the lowest completion of pre-transition value enhancement (~22%). More than half plan near-term exits, yet substantial shares lack recent valuations or completed estate plans. Preference leans toward external sales. Personal, financial, and business readiness scores lag the other cohorts.
Generation X reports higher education (~70%) and moderate readiness. They value autonomy and adaptability, yet only about 11% have formed a full formal advisory team. Exit planning ranks as a priority for a majority, but written transition plans remain incomplete for many.
Millennials show the highest education rates (~85%) and strongest self-rated readiness. They favor internal transitions (family, management, ESOP) and “boomerang” sequences—build, exit, reinvest. Even here, formal written action plans and completed value-enhancement projects are not universal. “Too busy” remains the leading stated reason for inaction across all groups.
Education and intention do not close the Working Owner Discount. Systems do. Younger owners who treat exit planning as ongoing strategy still leave value on the table when the operating system lives in the founder’s head. Owners closer to exit who have delayed face compressed timelines and forced outcomes. Across the board, only a small minority have a complete advisory team (financial advisor, attorney, accountant, and value-growth specialist) in place.
The Systems That Remove the Discount
Stratford’s five-part framework maps directly onto the practices that correlate with higher multiples and faster closes:
Genuine second-tier management — Recruit or promote a non-family senior manager with real decision rights over customers, operations, or finance. Cosmetic titles do not count; the authority must be exercised and decisions allowed to differ from the founder’s within defined parameters. This signals maturity and reduces continuity risk.
Documented critical processes — A transfer binder of SOPs covering production or service delivery, quality standards, vendor protocols, customer histories, and decision frameworks. This converts tacit knowledge into institutional assets and is linked to the 0.25× sales-multiple lift. Focus especially on infrequent but high-impact scenarios where institutional memory normally lives only with the owner.
Manager-level performance systems — Visible KPIs (on-time delivery, margin variance, customer retention, scrap or error rates, pipeline conversion) that demonstrate repeatability beyond the founder’s intuition. Data visibility creates accountability that survives the founder’s absence.
Phased leadership transition — Begin transferring responsibilities 12–18 months before any process, with a documented period of independent operation (ideally at least six months of proven results without founder input). Pre-transitioned structures close deals faster and with fewer post-LOI surprises.
Clean financials — Remove personal expenses, owner leases, and family payroll well before marketing so normalized EBITDA is defensible and diligence friction drops. Overlap between personal and business spending is a common diligence red flag that slows deals and reduces normalized earnings.
These are operating-system installations, not advice sessions. For founder-led companies in the $1–25 million range, the practical sequence is diagnose the current dependency cost, design the architecture across people, revenue, and process layers, install standards and scoreboards the team owns, then coach the shift from operator to owner-investor.
What This Means for Operators Who Still Cannot Leave
Most external risks (industry cycles, customer concentration outside the founder, macro conditions) are only partially controllable. Owner dependency is not. The businesses that clear the higher multiple are those in which the team runs the standards, processes are documented and followed, and the founder’s role has already moved from daily operator to owner-investor.
If every escalation, key relationship, and exception still routes through you, the market is already applying the Working Owner Discount. The data is clear on both the size of the gap and the practices that close it. The only variable left is whether the systems get installed early enough for the higher valuation to be proven rather than promised.
Frequently Asked Questions
What is the Working Owner Discount? A valuation penalty buyers apply when the owner remains central to daily operations, customer relationships, and decision-making. In the Stratford Analytics manufacturing sample, median EBITDA multiples were 4.0× for working-owner firms versus 7.5× for professionally managed peers.
How much does owner dependency typically reduce a business’s sale price? In the large manufacturing dataset, roughly 43–47% on key multiples. Stratford Analytics estimates the discount can reduce exit proceeds by 25–40%, and that professionalizing can capture 1–3× EBITDA in valuation premium, plus longer closes and a higher share of deferred consideration.
Can the discount be removed? Yes. Documented processes, genuine management depth with decision rights, and a phased transfer of authority correlate with higher multiples and faster transactions. The changes must be demonstrated, not cosmetic.
Does this apply outside manufacturing? The magnitude varies by industry and size, but the mechanism is consistent: buyers discount continuity and scalability risk whenever the founder is the operating system. Founder-led companies in the $1–25 million range are the most exposed.
How long does it take to eliminate most of the discount? Meaningful reduction typically requires 12–24 months of deliberate professionalization so that independent performance can be shown to buyers.
What is the highest-ROI action for most founder-led companies in this range? Install genuine second-tier management authority and document the critical processes that currently live only in the founder’s head. These two steps address the largest share of continuity and customer risk and show up directly in diligence and multiple discussions.
